Part 5 of 6

Title VII and Church Employment Practices

How the Supreme Courtโ€™s interpretation of Title VIIโ€™s term โ€œsexโ€ affects church employment.

Last Reviewed: February 10, 2026

Title VII of the Civil Rights Act of 1964 protects workers from discrimination based on race, color, religion, sex, or national origin. Since Title VIIโ€™s inception, the statute has included an exemption for โ€œreligious organizations.โ€

This exemption became more critical for many churches after the US Supreme Court interpreted Title VIIโ€™s term โ€œsexโ€ to include sexual orientation, sexual perception, gender identity, and transgender individuals (Bostock v. Clayton County, 140 S. Ct. 1731 (2020). But, the Supreme Court stated that its decision should not apply to religious organizations.

The Courtโ€™s words regarding the religious exemption bring little comfort to many in the religious community. But the Court did not indicate how it might rule regarding the religious exemption and the new definition of โ€œsex.โ€ Churches and the courts had already struggled with the application of the exemption for religious organizations. Now they face greater challenges in determining its application to the employment practices of religious organizations. This is especially true of the new definition of โ€œsex,โ€ if compliance with the new definition violates an organization’s religious beliefs.

This article examines the scope of this exemption and explores how the statute applies to churches and religious ministries.

History of Title VII

In 1963, President Kennedy asked Congress to pass comprehensive civil rights legislation. The Civil Rights Act of 1964 was passed the following year. The statute protected voting rights and prohibited discrimination in federal programs and public accommodations.

The Civil Rights Act was controversial from its initial drafting, with many in Congress opposing one part or another. Like many other difficult-to-pass bills, the bill was altered to gain enough congressional support to make it into law. For example, since the Tenth Amendment of the US Constitution limits the federal authority to matters of interstate commerce, Title VII was limited to employers engaged in interstate commerce with 15 or more employees for each workday during 20 weeks of a calendar year (42 U.S.C. ยง 2000e-2(a), et seq).

Note. The italics used in the quoted matter in the following section have been added for emphasis.

Another sticking point was its application to churches and other religious employers. The First Amendment of the US Constitution prohibits Congress from passing statutes restricting the free exercise of religion. The House Judiciary Committee requested a complete exemption for religious organizations from Title VII to reflect this constitutional requirement. The Senate disagreed, believing the request was broader than necessary under the First Amendment.

The Senate changed the exemption to read:

[Title VII] shall not apply … to a religious corporation, association, or society with respect to the employment of individuals of a particular religion to perform work connected with the carrying on by such[organization] of its religious activities.

Afterward, the House agreed to the amended exemption, and President Johnson signed the Civil Rights Act into law.

But problems immediately arose in the enforcement of the religious exemption. The US Department of Labor (DOL) interpreted the exemption to apply only to members of that religious group employed to perform religious activities. This interpretation forced the DOL to decide what activities were religious and how many religious activities were required before the exemption could be applied to a specific position.

Congress reconsidered the religious organization exemption in 1972. The issue arose in the creation of the Equal Employment Opportunity Commission (EEOC). The final bill creating the EEOC deleted the word โ€œreligiousโ€ before the word โ€œactivitiesโ€ in the statute.

Currently, Title VII states that it โ€œshall not apply … to a religious corporation, association, or society with respect to the employment of individuals of a particular religion to perform work connected with the carrying on by such … [organization] of its activitiesโ€ (42 U.S.C. ยง 2000e-1(a)).

The United States Congress Conference Report after the 1972 amendment stated:

The limited exemption … for religious corporations, associations, educational institutions or societies has been broadened to allow such entities to employ individuals of a particular religion in all their activities instead of the present limitation to religious activities.

The Conference Report also noted, however, that religious organizations โ€œremain subject to the provisions of Title VII with regard to race, color, sex or national origin.โ€

What qualifies as a religious organization for a Title VII exemption?

Since 1972, the courts have created tests and criteria to determine a โ€œreligious organizationโ€ for Title VIIโ€™s exemption.

Lack of congressional guidance has left the exemption open to different interpretations by DOL, EEOC, law professors, and the courts. Even within some judicial districts, the judges do not interpret the exemption consistently. No universally accepted definition exists to identify a religious organization used in Title VII.

No single test exists, and no test is used universally for determining whether an entity qualifies as a religious organization. An IRS determination that the organization has church status has little or no bearing on whether the organization meets the Title VII religious organization test because the tests are different. After making that observation, the courts will typically look at, and weigh, one or more of these factors:

  1. whether the entity operates for a profit,
  2. whether it produces a secular product,
  3. whether the entityโ€™s articles of incorporation or other pertinent documents state a religious purpose,
  4. whether it is owned, affiliated with or financially supported by a formally religious entity such as a church or synagogue,
  5. whether a formally religious entity participates in the [entityโ€™s] management, for instance, by having representatives on the board of trustees,
  6. whether the entity holds itself out to the public as secular or sectarian,
  7. whether the entity regularly includes prayer or other forms of worship in its activities,
  8. whether it includes religious instruction in its curriculum, to the extent it is an educational institution, and
  9. whether its membership is made up of coreligionists.

LeBoon v. Lancaster Jewish Community Center, 503 F.3d 217, 226 (3d Cir. 2007).

While traditional churches may easily qualify, parachurch ministries have more difficulty. For example, the US Supreme Court rejected an appeal from the Washington Supreme Court, finding the state exemption from its state nondiscrimination statute for โ€œreligious organizationsโ€ did not protect the Seattle Gospel Mission from liability for failing to hire an attorney in a same-sex marriage case (Seattle Gospel Mission v. Woods, 142 S.Ct. 1094 (2022)).

Likewise, another court found that a downtown mission organization was not a religious organization for Title VII because it was not affiliated with a particular denomination or church (Scaffidi v. New Orleans Mission, 2020 WL 1531266 (E.D. La. 2020)).

In contrast, the Ninth Circuit Court of Appeals held that World Vision qualified for the religious organization exemption from Title VII. In a 2โ€“1 decision, the court held that World Vision could terminate three employees because they changed their religious beliefs (Spencer v. World Vision, Inc., 619 F.3d 1109 (9th Cir. 2010)).

But the three judges could not agree on the test to evaluate whether an entity meets the definition of a religious organization. The dissenting judge would have limited the exemption to organizations that gather members together for prayer and religious instruction.

One of the judges affirmed World Visionโ€™s status under this test:

(1) does the organization self-identify as a religious organization in its governing documents?

(2) does the organization engage in religious activities to further its religious purposes, and

(3) does it hold itself out to the public as a religious organization?

The other affirming judge added another factor to the above three-item list: Does the organization not engage in the exchange of goods and services for money?

From these brief examples, one can conclude that churches and parachurch ministries should examine the nine criteria listed above. From there, the church may determine how they can best meet the criteria for obtaining a Title VII exemption.

At a minimum, they should review their governing documents, incorporate a statement of beliefs into governance documents and policies, and represent to the public that they are a religious organization.

Title VIIโ€™s application

Once an organization believes it meets the qualifications required to be classified as a religious organization, it must determine what portion of Title VIIโ€™s nondiscrimination provisions apply.

An examination of the applicable court cases reveals three plausible, but inconsistent, interpretations (discussed below).

Understanding the foundation for various interpretations requires some basic understanding of the rules for statutory interpretation. All three interpretations utilize differing rules for statutory interpretation to reach different conclusions.

Since the US Supreme Court has not instructed the lower courts on the correct or preferred way to interpret the Title VII religious organization exemption, each court is free to interpret the statute using the US Supreme Court rules for statutory interpretation.

The US Supreme Court has adopted a general guide to statutory interpretation for use by the lower courts.

A complete review of the statutory interpretation rules isnโ€™t possible for this article.

However, a few relevant rules should be noted.

First, the law should be given its plain meaning whenever possible.

Second, plain meaning should not be used if the language is ambiguous. Ambiguous means a reader could reasonably interpret the language in two or more ways.

If the language is ambiguous, the court should interpret the statute to give effect to every word because every word has a purpose.

If the statute remains ambiguous, the court should choose the interpretation to implement the congressional intent based on the legislative history.

Here, then, is a discussion of each interpretation and what each one might mean for a courtโ€™s decision.

Note. The italics used in the quoted matter in this section have been added for emphasis.

Interpretation 1: Textual or religiously motivated interpretation

The first interpretation is called the textual or religiously motivated interpretation. It indicates that the statuteโ€™s plain meaning requires that no part of Title VII applies to the employment practices of religious organizations.

Key point. This interpretation utilizes the first statutory interpretation rule: The statute should be given its plain meaning whenever possible.

The plain language of Title VII states that it โ€œshall not apply … to a religious corporation, association, or society with respect to the employment of individuals of a particular religion to perform work connected with the carrying on by such … [organization] of its activitiesโ€ (42 U.S.C. ยง 2000e-1(a)). If this interpretation is utilized, no other rules of statutory interpretation apply.

Under this interpretation, none of Title VII applies to the religious organization. A church is free to discriminate regarding applicants and employees based on race, color, religion, sex, or national origin. Based on this interpretation, if the church chooses not to hire a woman for a position because she is a woman, it is free to do so.

However, Congress has twice consideredโ€”and rejectedโ€”a blanket exemption for religious organizations. If a court found that the statute is ambiguous, the congressional rejection of this interpretation could invalidate this interpretation. Further, this interpretation potentially ignores the โ€œemployment of individuals of a particular religionโ€ language.

Example. In 2023, the Fifth Circuit Court of Appeals left intact a lower courtโ€™s ruling in which it used the textual or religiously motivated interpretation method to find that Bear Creek Bible Church was exempt from Title VII as a religious organization (Briarwood Management, Inc. v. EEOC, ____ F.3d _______ (5th Cir. 2023)). This decision means the church could discriminate based on sexual orientation, sexual perception, gender identity, and transgender status without violating Title VII. The Fifth Circuit panel also ruled that the church could have different dress codes for men and women and require that employees use the bathroom associated with their biological gender.

Interpretation 2: The coreligionist interpretation

The coreligionist interpretation indicates that religious organizations may refuse to hire anyone not part of their denomination or church group.

Key point. This interpretation allows religious organizations to restrict employment to their denomination or church group.

The plain language of Title VII states that it โ€œshall not apply … to a religious corporation, association, or society with respect to the employment of individuals of a particular religion to perform work connected with the carrying on by such … [organization] of its activitiesโ€ (42 U.S.C. ยง 2000e-1(a)).

Applications vary

Some courts believe this language is ambiguous because it does not explicitly address how the exemption applies to the other protected classes. Some courts then looked at the legislative history. The 1972 amendment to Title VII added a statutory definition of religion. It states, โ€œThe term โ€œreligionโ€ includes all aspects of religious observance and practice, as well as beliefโ€ (42 U.S.C. ยง 2000e-1(j)).

The authors of the 1972 amendment claimed the new language was to protect the religious rights of employeesโ€”not to expand the religious exemption of employers. Supposedly, the amended statute protected all religious organization employees instead of only those involved in religious activity.

Some courts have used this background in interpreting the Title VII religious organization exemption to prevent the application of Title VII to religious organizations only employing individuals who are part of the same denomination or church group.

This interpretation means that a Baptist church can require all its employees to be Baptist. It can also terminate an employee for failing to adhere to Baptist beliefs. It can refuse to hire Methodists. But the Baptist church must not discriminate against the other Title VII protected classes unless its discrimination is related to the churchโ€™s sincerely held religious beliefs.

Caution. All violations of such beliefs should provide comparable disciplinary actions. The inconsistent application of variances from their religious beliefs could lead a church into a potential Title VII violation if one of the protected classes is involved.

The US Supreme Court used this interpretation to allow a church to fire a gym worker at a facility owned by the church for failing to adhere to church beliefs and requirements (Corporation of the Presiding Bishop of The Church of Jesus Christ of Latter-day Saints v. Amos, 483 U.S. 327 (1987)).

The Ninth Circuit Court of Appeals has affirmed this approach twice. The Fourth Circuit Court of Appeals has also adopted this approach.

Interpretation 3: Belief and conduct interpretation

The third interpretation, called the belief and conduct interpretation, indicates that religious employers may discriminate based on religious beliefs as long as those beliefs do not contradict the other protected classes of race, color, sex, or national origin.

Key point. This line of interpretation rejects the coreligionist and textual interpretation cases.

With the addition of the definition of religion, some courts believe that the artificial lines of church association were eliminated. Accordingly, no statutory basis exists for limiting the religious organization exemption to those who employ only individuals who are part of the denomination or church group.

Since the purpose of Title VII is to protect workers from specific types of discrimination, the exclusions from its coverage should be narrowly interpreted. These courtsโ€™ interpretation means that religious organizations may discriminate only based on the employeeโ€™s self-identified religious beliefs and practices that vary from the employing religious organizationโ€”and only if those beliefs do not relate to another Title VII protected class.

Example. A court affirmed the right of a Christian school owned and operated by a church to terminate a teacher who remarried after a divorce, contrary to the churchโ€™s teaching.

While the teacher was not of the same faith as the employer, she had agreed to follow the churchโ€™s teachings and beliefs while employed by the school. Since the teacherโ€™s religious beliefs differed from the employerโ€™s and were evidenced by her actions, the school could terminate her because it met the definition of a religious educational employer (Little v. Wuerl, 929 F.2d 944 (3d Cir. 1991).

With this interpretation, all potential applicants must review the organizationโ€™s religious beliefs before applying for the job and determine if such beliefs align with the applicantsโ€™ beliefs. Religious organizations may require potential applicants to take this step before applying for a position to attempt to come into alignment with this interpretation.

Suggestions for determining how to comply

Each church must determine how it will comply with Title VII. Here are four suggestions.

Purchase employment practices liability insurance

Every church with 15 or more employees should purchase employment practices liability insurance. This insurance benefits the church in two ways. First, it provides access to the insurance companyโ€™s risk management employment attorneys and HR professionals. Second, the insurance company will assist with the defense should an employee claim a Title VII violation. The policy should also cover employment related claims under the state equivalent of Title VII.

Identify ministerial exception positions

The church or ministry should distinguish and document ministerial exception positions from every other position. Since Title VII does not apply to the ministerial exception positions, the church does not face Title VII risk with those positions. (For more on this subject, see โ€œApplying the Ministerial Exception to Church Employees.โ€

Review all pertinent documents

The church should review its governance documents, EEOC statements made by the church, the churchโ€™s employee handbook, and the churchโ€™s employment-related policies. If the EEOC statement includes โ€œreligionโ€ as a protected class, the church will have a hard time claiming that it may discriminate based on religion. Further, the church should qualify its EEOC statement to say the church follows Title VII only to the extent that Title VII applies to it.

The church should also review its job descriptions. The job description should include a requirement that employees comply with its doctrine and beliefs in their daily lives. If the church can show that this requirement is necessary to accomplish its purposes and mission, the church may be able to argue the bona fide occupational qualification exception exempts that employee from the application of Title VII.

Require employment applicants to agree with the churchโ€™s beliefs statement and code of conduct

The church should require all potential applicants and church employees to agree with the churchโ€™s statement of beliefs and code of conduct before applying for any position. The employee handbook and employment policies should require employees to follow the churchโ€™s sincerely held beliefs and its code of conduct, and disciplinary action should occur for all identified violations. This practice will isolate the Title VII issue to religious discrimination. Religious discrimination cases without considering the other protected classes will likely be easier to defend.

Preparation creates clarity in employment practices

Title VII may or may not apply to the church or a religious ministry. Title VII may or may not apply to some employment positions. With this statute, it is not always clear. And similar state employment laws may include a different definition of religious organization and protected classes of employees.

If the church is unsuccessful in asserting its exemption from Title VII, the church may want to consider asserting its rights under the Religious Freedom Restoration Act. This statute is intended to protect religious organizations from government overreach.  Some courts have used this Act to void claims under Title VII. The church should document the ways enforcement of Title VII intrudes into the religious practices of the church. 

The church may also want to consider how to use the โ€œchurch autonomy doctrineโ€ as a defense against a Title VII action.  The church autonomy doctrine holds that no governmental authority can intrude into the internal decision making of a church, absent fraud and few other exceptions. The church should document how hiring and other employment decisions are made as part of their religious practices. The church should require employees to assist with accomplishing its religious mission and follow its doctrine.

Preparation creates clarity for employment decisions, so a church or ministry must decide its risk tolerance, especially when the churchโ€™s sincerely held religious beliefs conflict with Title VIIโ€™s protected classes of employees. The church must also indicate whether it believes Title VII applies to all nonministerial exception positions. The church must document any other defenses it may want to assert, such as the Religious Freedom Restoration Act or the church autonomy doctrine. As part of its working through this issue, every church should engage competent legal counsel to assist in drafting employment practices consistent with its religious beliefs.
Frank Sommerville is both a CPA and attorney, and a longtime Editorial Advisor for Church Law & Tax.

October Key Tax Dates 2022

Deadline for church employees with six-month extensions for filing 2021 tax returnsโ€”and other key dates to note.

Monthly Requirements

If your church or organization reported withheld taxes of $50,000 or less during the most recent lookback period (for 2022 the lookback period is July 1, 2020, through June 30, 2021), then withheld payroll taxes are deposited monthly. Monthly deposits are due by the 15th day of the following month.

Note, however, that if withheld taxes are less than $2,500 at the end of any calendar quarter (March 31, June 30, September 30, or December 31), the church need not deposit the taxes. Instead, it can pay the total withheld taxes directly to the IRS with its quarterly Form 941. Withheld taxes include federal income taxes withheld from the employeeโ€™s wages, the employeeโ€™s share of Social Security and Medicare taxes, and the employerโ€™s share of Social Security and Medicare taxes.

Semiweekly requirements

If your church or organization reported withheld taxes of more than $50,000 during the most recent lookback period (for 2022 the lookback period is July 1, 2020, through June 30, 2021), then the withheld payroll taxes are deposited semiweekly.

This means that for paydays falling on Wednesday, Thursday, or Friday, the payroll taxes must be deposited on or by the following Wednesday. For all other paydays, the payroll taxes must be deposited on the Friday following the payday.

Note further that large employers having withheld taxes of $100,000 or more at the end of any day must deposit the taxes by the next banking day. The deposit days are based on the timing of the employerโ€™s payroll. Withheld taxes include federal income taxes withheld from the employeeโ€™s wages, the employeeโ€™s share of Social Security and Medicare taxes, and the employerโ€™s share of Social Security and Medicare taxes.

October 17, 2022: Form 1040 due for taxpayers who filed for a six-month extension

Last day to file a 2021 federal income tax return (Form 1040) for taxpayers who obtained an automatic six-month extension by filing a Form 4868 by April 18, 2022 (April 19 if you live in Maine or Massachusetts).

October 30, 2022: File employer exemption (Form 8274)

Churches hiring their first nonminister employee between July 1 and September 30 may exempt themselves from the employerโ€™s share of FICA (Social Security) taxes by filing Form 8274 by this date. (Nonminister employees are thereafter treated as self-employed for Social Security purposes).

The exemption is only available to churches that are opposed on the basis of religious principles to paying the employerโ€™s share of FICA taxes.

October 31, 2022: File quarterly federal tax return (Form 941) with payment

Churches having nonminister employees (or one or more ministers who report their federal income taxes as employees and who have elected voluntary withholding) must file an employerโ€™s quarterly federal tax return (Form 941) for the third calendar quarter by this date.

Enclose a check in the total amount of all withheld taxes (withheld income taxes, withheld FICA taxes paid by the employee, and the employerโ€™s share of FICA taxes) if less than $2,500 on September 30, 2022.

Richard R. Hammar is an attorney, CPA and author specializing in legal and tax issues for churches and clergy.

On-Demand Webinar

Handling A Child Abuse Allegation in Your Church

Planning well so that your ministry responds well if the unthinkable ever arises.

Loading the player...

Churches across the country continue to face allegations of child abuse. Real people are behind these allegations- those who file complaints, those who are accused, as well as those in positions of authority who must respond.

In most cases, the gospel in not reflected in the responses. Fallout is significant for everyone involved, and Church leaders must find a way to do better with such high stakes- whether spiritual, mental, relational, or legal.

Watch this video to hear from recognized experts in church leadership and law about responding to allegations, including abuse reporting, investigations, victim care, and more.

Panelists:

Jeff Dalrymple | Executive Director, Evangelical Council For Abuse Prevention

Robert Showers | Attorney & Principal Partner, Simms Showers

Sally Wagenmaker | Attorney & Partner, Wagenmaker & Oberly

Theresa Sidebotham | Attorney & Founder, Telios Law

Reading & Resources:โ€ฏ

Download the resources and templates mentioned in this webinar below. Or read one of the articles to get a handle on the basics of developing fair compensation in your ministry.

Key Tax Dates September 2022

Make quarterly estimated payments and meet monthly or semiweekly requirements.

Monthly requirements

If your church or organization reported withheld taxes of $50,000 or less during the most recent lookback period (for 2022, the lookback period is July 1, 2020, through June 30, 2021), then withheld payroll taxes are deposited monthly. Monthly deposits are due by the 15th day of the following month.

Note, however, that if withheld taxes are less than $2,500 at the end of any calendar quarter (March 31, June 30, September 30, or December 31), the church need not deposit the taxes.

Instead, it can pay the total withheld taxes directly to the IRS with its quarterly Form 941. Withheld taxes include federal income taxes withheld from employee wages, the employeeโ€™s share of Social Security and Medicare taxes, and the employerโ€™s share of Social Security and Medicare taxes.

Semiweekly requirements

If your church or organization reported withheld taxes of more than $50,000 during the most recent lookback period (for 2022, the lookback period is July 1, 2020, through June 30, 2021), then the withheld payroll taxes are deposited semiweekly.

This means that for paydays falling on Wednesday, Thursday, or Friday, the payroll taxes must be deposited on or by the following Wednesday. For all other paydays, the payroll taxes must be deposited on the Friday following the payday.

Note further that large employers having withheld taxes of $100,000 or more at the end of any day must deposit the taxes by the next banking day. The deposit days are based on the timing of the employerโ€™s payroll. Withheld taxes include federal income taxes withheld from employee wages, the employeeโ€™s share of Social Security and Medicare taxes, and the employerโ€™s share of Social Security and Medicare taxes.

September 15, 2022: Quarterly estimated tax payments for certain employees and churches

Filing for certain ministers and self-employed workers

Ministers (who have not elected voluntary withholding) and self-employed workers must file their third quarterly estimated federal tax payment for 2022 by this date. A similar rule applies in many states to payments of estimated state taxes.

Nonminister employees of churches that filed a timely Form 8274 (waiving the churchโ€™s obligation to withhold and pay FICA taxes) are treated as self-employed for Social Security, and as a result are subject to the estimated tax deadlines with respect to their self-employment (Social Security) taxes unless they ask their employing church to withhold an additional amount of income taxes from each paycheck that will be sufficient to cover self-employment taxes. Use a new Form W-4 to make this request (the additional withholding is reported on line 4(c)).

Payments for unrelated business income tax liability

A church must make quarterly estimated tax payments if it expects an unrelated business income tax liability for the year to be $500 or more. Use IRS Form 990-W to figure your estimated taxes. Quarterly estimated tax payments of one-fourth of the total tax liability are due by April 18 (April 19 if you live in Maine or Massachusetts), June 15, September 15, and December 15, 2022, for churches on a calendar-year basis. Deposit quarterly tax payments electronically using the Electronic Federal Tax Payment System (EFTPS).

Richard R. Hammar is an attorney, CPA and author specializing in legal and tax issues for churches and clergy.

Key Tax Dates August 2022

File employerโ€™s quarterly federal tax return and meet monthly or semiweekly requirements.

Monthly requirements

If your church or organization reported withheld taxes of $50,000 or less during the most recent lookback period (for 2022, the lookback period is July 1, 2020, through June 30, 2021), then withheld payroll taxes are deposited monthly. Monthly deposits are due by the 15th day of the following month.

Note, however, that if withheld taxes are less than $2,500 at the end of any calendar quarter (March 31, June 30, September 30, or December 31), the church or organization need not deposit the taxes.

Instead, it can pay the total withheld taxes directly to the IRS with its quarterly Form 941. Withheld taxes include federal income taxes withheld from employee wages, the employeeโ€™s share of Social Security and Medicare taxes, and the employerโ€™s share of Social Security and Medicare taxes.

Semiweekly requirements

If your church or organization reported withheld taxes of more than $50,000 during the most recent lookback period (for 2022, the lookback period is July 1, 2020, through June 30, 2021), then the withheld payroll taxes are deposited semiweekly.

This means that for paydays falling on Wednesday, Thursday, or Friday, the payroll taxes must be deposited on or by the following Wednesday. For all other paydays, the payroll taxes must be deposited on the Friday following the payday.

Note further that large employers having withheld taxes of $100,000 or more at the end of any day must deposit the taxes by the next banking day. The deposit days are based on the timing of the employerโ€™s payroll. Withheld taxes include federal income taxes withheld from employee wages, the employeeโ€™s share of Social Security and Medicare taxes, and the employerโ€™s share of Social Security and Medicare taxes.

August 10, 2022: Employerโ€™s quarterly federal tax returnโ€”Form 941

Churches having nonminister employees (or one or more ministers who report their federal income taxes as employees and who have elected voluntary withholding) may file their employer’s quarterly federal tax return (Form 941) by this date instead of July 31 if all taxes for the second calendar quarter have been deposited in full and on time.

Richard R. Hammar is an attorney, CPA and author specializing in legal and tax issues for churches and clergy.

Postgame Prayers Protected by First Amendment, Supreme Court Says

Supreme Court says postgame prayers protected by First Amendment while also striking down controversial “Lemon test.”

Last Reviewed: July 16, 2025

Kennedy v. Bremerton School District (2022)

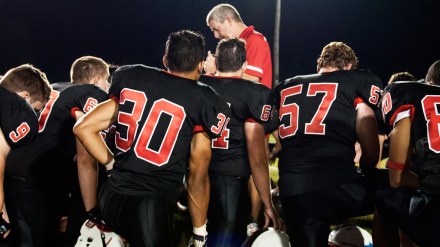
In a 6โ€“3 decision, the U.S. Supreme Court ruled in favor of a high school football coach whose postgame prayers on the field were challenged by his employer. The Court found that the school district violated the coachโ€™s rights under both the Free Exercise and Free Speech Clauses of the First Amendment.

โ€œA government entity sought to punish an individual for engaging in a brief, quiet, personal religious observance doubly protected by the Free Exercise and Free Speech Clauses.โ€ โ€” Supreme Court majority opinion

The ruling also overturned a long-standing judicial test used in Establishment Clause cases, reshaping how courts evaluate religion-related disputes involving government actors.


Background: Coach Kennedyโ€™s Prayers

  • Joseph Kennedy, a Marine Corps veteran, began coaching football at Bremerton High School in Washington in 2008.
  • After games, Kennedy would kneel at midfield and offer a brief, silent prayer, usually lasting about 30 seconds.
  • Initially, Kennedy prayed alone. Over time, players joined voluntarilyโ€”sometimes including opponents.
  • Kennedy occasionally added motivational messages to his prayers when students were present.

For more than seven years, no complaints were made. That changed in September 2015, when the districtโ€™s superintendent instructed Kennedy to stop praying on school grounds after games.


  • Kennedy paused his prayers but later resumed them, citing a religious conviction and sending a legal letter requesting the right to โ€œprivate religious expression.โ€
  • The district rejected the request, warning that any public religious displayโ€”even done privatelyโ€”would appear to endorse religion and thus violate the Establishment Clause.
  • Despite complying with previous orders, Kennedy resumed praying quietly after three October 2015 games.
  • Following these actions, the district:
    • Placed him on paid administrative leave
    • Barred him from all football-related activities
    • Issued a poor performance evaluation, citing policy violations
  • Kennedy did not return the following season.

Importantly, the district acknowledged:

  • No evidence of coercion of students to join in prayer
  • Kennedy had complied with requests to stop leading players in postgame prayer

Kennedy Sues: First Amendment Claims

Kennedy sued in federal court, alleging violations of:

  • The Free Speech Clause
  • The Free Exercise Clause

Lower courts sided with the district. The Supreme Court agreed to hear the case and ultimately ruled in Kennedyโ€™s favor.


Free Exercise Clause: Two Ways to Prove a Violation

The Court explained that plaintiffs can show a violation of the Free Exercise Clause by:

  1. Demonstrating hostility to religion, such as public officials showing bias (e.g., Masterpiece Cakeshop v. Colorado Civil Rights Commission, 2018).
  2. Proving non-neutral or non-general policies that burden religious practice.

The Court ruled that Kennedy satisfied the second test:

โ€œThe Districtโ€™s challenged policies were neither neutral nor generally applicable โ€ฆ Prohibiting a religious practice was thus the Districtโ€™s unquestioned object.โ€ โ€” Majority opinion


Free Speech Clause: Private or Government Speech?

The key legal question: Was Kennedyโ€™s prayer private speech or government speech?

The Court found that:

  • Kennedy was not speaking as a government employee.
  • His prayer did not involve coaching duties or school policy.
  • The act occurred during a brief window when coaches attended to personal matters.

โ€œSimply put: Mr. Kennedyโ€™s prayers did not owe their existence to Mr. Kennedyโ€™s responsibilities as a public employee.โ€

As a result, the districtโ€™s restrictions violated Kennedyโ€™s free speech rights.


The Courtโ€™s Conclusion

To justify its restrictions, the district needed to prove it had a compelling interest and that its actions were narrowly tailored. The Court found the district failed to do so.

โ€œRespect for religious expressions is indispensable to life in a free and diverse Republic โ€ฆ [This case involved] a brief, quiet, personal religious observance doubly protected by the Free Exercise and Free Speech Clauses.โ€


Major Shift: The End of the Lemon Test

The decision also struck down the long-standing Lemon test from Lemon v. Kurtzman (1971), which courts used to evaluate Establishment Clause cases.

The Lemon Testโ€™s 3 Prongs:

  1. Government action must have a secular purpose
  2. Its effect must neither advance nor inhibit religion
  3. It must avoid excessive entanglement with religion

Over time, courts also used a โ€œreasonable observerโ€ endorsement test, asking whether someone might see the action as religious endorsement.

The Court said these tests:

  • Invited legal chaos
  • Led to inconsistent rulings
  • Created a โ€œminefieldโ€ for public officials

โ€œ[T]he Establishment Clause must be interpreted by reference to historical practices and understandings โ€ฆ consistent with the understanding of the Founding Fathers.โ€


Conclusion: Expanded Protections for Religious Liberty

This landmark ruling affirms the constitutional protections of free speech and free religious expression, especially for government employees acting in a private capacity.

Most significantly, it marks the formal end of the Lemon testโ€”reshaping how courts will interpret government interaction with religion in the years ahead.

Case citation: Kennedy v. Bremerton Sch. Dist., 142 S. Ct. 2407 (2022)

We’ve used a combination of AI and human review to make this content easier to read and understand.

Richard R. Hammar is an attorney, CPA and author specializing in legal and tax issues for churches and clergy.
Related Topics:

Maineโ€™s Tuition Assistance Rule Violated the First Amendment, Supreme Court Says

Maine’s tuition assistance rule barred use of state funds at religious schools, which violated the First Amendment, Court says.

A โ€œnonsectarianโ€ requirement included with a tuition assistance program offered in Maine violated the First Amendmentโ€™s Free Exercise of Religion Clause, the United States Supreme Court ruled last month.

The 6โ€“3 decision in Carson v. Makin may make it easier for religious schools nationwide, at least in some cases, to benefit from financial aid made available to use at other public and private schools.

Background

Maine has enacted a program of tuition assistance for parents who live in school districts that do not operate a secondary school of their own. Under the program, parents designate the secondary school they would like their child to attendโ€”public or privateโ€”and the school district transmits payments to that school to help defray the costs of tuition.

Most private schools are eligible to receive the payments, so long as they are โ€œnonsectarian,โ€ meaning the schools are not religious in nature. The requirement raised two questions: Does such a restriction violate the First Amendmentโ€™s Free Exercise Clause? And does the absence of such a restriction violate the First Amendmentโ€™s Establishment Clause prohibiting state sponsorship of religion?

The Supreme Court concluded the presence of the requirement did violate the Free Exercise Clause, while also finding the absence of the requirement would not violate the Establishment Clause.

The Court said:

A neutral benefit program in which public funds flow to religious organizations through the independent choices of private benefit recipients does not offend the Establishment Clause. . . .

[Justice Breyerโ€™s dissenting opinion] stresses the importance of โ€œgovernment neutralityโ€ when it comes to religious matters, but there is nothing neutral about Maineโ€™s program. The State pays tuition for certain students at private schools so long as the schools are not religious. That is discrimination against religion. A Stateโ€™s antiestablishment interest does not justify enactments that exclude some members of the community from an otherwise generally available public benefit because of their religious exercise.

The Court turned to two past rulings

In reaching its decision, the Court relied on two of its previous decisionsโ€”Trinity Lutheran and Espinoza.

Trinity Lutheran Church v. Comer

In Trinity Lutheran Church v. Comer, 137 S.Ct. 2012 (2017), the Court considered a Missouri program that offered grants to qualifying nonprofit organizations that installed cushioning playground surfaces made from recycled rubber tires. The Missouri Department of Natural Resources maintained an express policy of denying such grants to any applicant owned or controlled by a church, sect, or other religious entity.

The Trinity Lutheran Church Child Learning Center applied for a grant to resurface its gravel playground, but the department denied funding on the ground that the center was operated by a church. The Court deemed it โ€œunremarkable in light of our prior decisionsโ€ to conclude that the Free Exercise Clause did not permit Missouri to โ€œexpressly discriminate against otherwise eligible recipients by disqualifying them from a public benefit solely because of their religious character.โ€

While it was true that Trinity Lutheran remained โ€œfree to continue operating as a church,โ€ it could enjoy that freedom only โ€œat the cost of automatic and absolute exclusion from the benefits of a public program for which the Center [was] otherwise fully qualified.โ€ Such discrimination, the Court said, was โ€œodious to our Constitutionโ€ and could not stand.

Espinoza v. Montana Department of Revenue

In Espinoza v. Montana Department of Revenue, 140 S.Ct. 2246 (2020), the Supreme Court held that a provision of the Montana Constitution barring government aid to any school โ€œcontrolled in whole or in part by any church, sect, or denomination,โ€ violated the First Amendmentโ€™s Free Exercise of Religion Clause by prohibiting families from using otherwise available scholarship funds at the religious schools of their choosing.

The Court observed that โ€œa State need not subsidize private education [but] once a State decides to do so, it cannot disqualify some private schools solely because they are religious.โ€ The Court concluded:

Montanaโ€™s no-aid provision bars religious schools from public benefits solely because of the religious character of the schools. The provision also bars parents who wish to send their children to a religious school from those same benefits, again solely because of the religious character of the school. . . . The proviยญsion plainly excludes schools from government aid solely beยญcause of religious status,โ€ [just as in Trinity Lutheran]. . . .

The Free Exยญercise [of religion] Clause protects against even โ€œindirect coercion,โ€ and a State โ€œpunishe[s] the free exercise of religionโ€ by disqualยญifying the religious from government aid as Montana did here. . . .

[The Constitution] condemns discrimination against religious schools and the families whose children attend them. They are โ€œmember[s] of the community too,โ€ and their exclusion from the scholarship program here is โ€œodiยญous to our Constitutionโ€ and โ€œcannot standโ€ (citing Trinity Lutheran).

The Courtโ€™s conclusion in Maine

The Court concluded in Maineโ€™s Carson case:

Maineโ€™s โ€œnonsectarianโ€ requirement for its otherwise generally available tuition assistance payments violates the Free Exercise Clause of the First Amendment. Regardless of how the benefit and restriction are described, the program operates to identify and exclude otherwise eligible schools on the basis of their religious exercise. The judgment of the Court of Appeals is reversed, and the case is remanded for further proceedings consistent with this opinion.

What this means for churches

What is the importance of this case? Most importantly, it will allow religious schools nationwide, at least in some cases, to benefit from financial aid made available to other schools (i.e., public and private secular schools).

Religious schools cannot be excluded from such aid solely on the basis of their religious status. As the Court concluded, religious schools are โ€œmembers of the community too,โ€ and their exclusion from the scholarship program here is โ€œodiยญous to our Constitutionโ€ and โ€œcannot standโ€ (citing Trinity Luยญtheran).

This case may contribute to a greater degree of school choice, depending on current and future state-enabling legislation.

Carson v. Makin, 596 U.S. ____ (2022)

Richard R. Hammar is an attorney, CPA and author specializing in legal and tax issues for churches and clergy.

Supreme Court: Religious Law Allows Clergy to be in Execution Chambers

Law protecting prisoners’ religious rights allows clergy to be present in execution chambers, Court says.

A prisoner scheduled to be executed in Texas requested that he be allowed to have his pastor present to provide โ€œspiritual comfort and guidance in his final moments.โ€ The state of Texas denied the request because it bars chaplains of any religion to enter an execution chamber.

After the denial by Texas, the prisoner sought legal relief for his request only to be denied by a federal district court and a court of appeals. The United States Supreme Court subsequently took up the case.

The Court, in an 8-1 majority, reversed the lower court decisions. Citing the Religious Land Use and Institutionalized Persons Act of 2000 (RLUIPA), it said the restrictions imposed by Texas were not based on โ€œa compelling governmental interest.โ€

This article will explore the Courtโ€™s analysis, and the general implications of the decision for chaplains and prison ministries.

Background

Pablo Castro worked the night shift at the Times Market convenience store in Corpus Christi, Texas. On July 19, 2004, Castro was outside closing up when John Ramirez and an accomplice approached him with a knife. Ramirez stabbed Castro 29 times, searched his pockets, and made off with $1.25. Castro died on the pavement, leaving behind 9 children and 14 grandchildren.

Ramirez fled to Mexico, where he evaded authorities for more than three years. In 2008, he was finally apprehended near the Mexican border. The state of Texas charged Ramirez with murdering Castro in the course of committing or attempting to commit robberyโ€”a capital offense. Ramirez admitted to killing Castro but denied the robbery that made the murder a capital crime. A jury disagreed, found Ramirez guilty, and sentenced him to death.

Texas scheduled Ramirezโ€™s execution for September 9, 2020. Ramirez asked to have his pastor accompany him into the execution chamber. Prison officials denied the request. They did so because, at the time, Texasโ€™s execution protocol barred all spiritual advisors from entering the chamber.

A prior version of the protocol had allowed access for prison chaplains, but at the time, Texas employed only Christian and Muslim chaplains. In 2019, when a Buddhist inmate sought to have his spiritual advisor join him in the execution chamber, Texas declined to grant the accommodation. In response, Texas also amended its execution protocol to bar all chaplains from entering the execution chamber so as not to discriminate among religions.

Turning to RLUIPA

Ramirez filed a lawsuit in federal court. He did not challenge his conviction or death sentence. Instead, he asked that his longtime pastor be allowed to pray with him and lay hands on him while he was being executed. He claimed that RLUIPA, a federal law, requires this accommodation.

Ramirez sought a preliminary injunction ordering Texas to permit his religious exercise if the state went forward with his execution. A federal district court and court of appeals declined to grant such relief. The United States Supreme Court agreed to hear the case on appeal.

Ramirezโ€™s complaint said that he was a Christian and had received religious guidance from Pastor Dana Moore since 2016. Ramirez is a member of Mooreโ€™s church in Corpus Christi.

Ramirez explained that he wanted his pastor โ€œto be present at the time of his execution to pray with him and provide spiritual comfort and guidance in his final moments,โ€ and that the pastor be permitted to โ€œlay handsโ€ on him and audibly โ€œpray overโ€ him while the execution was taking place. Ramirezโ€™s grievance explains that โ€œit is part of my faith to have my spiritual advisor lay hands on me anytime I am sick or dying.โ€

Texas denied this request on the ground that spiritual advisors are โ€œnot allowed to touch an inmate while inside the execution chamber.โ€

In reviewing the case, the Supreme Court described RLUIPA in this way:

No government shall impose a substantial burden on the religious exercise of a person residing in or confined to an institutionโ€”including state prisoners . . . unless the government demonstrates that imposition of the burden on that person (1) is in furtherance of a compelling governmental interest; and (2) is the least restrictive means of furthering that compelling governmental interest.

The Court concluded that any restriction on the ability of Ramirezโ€™s pastor to enter the execution chamber, lay hands on him, and audibly pray for him during the execution procedure would impose a substantial burden on his religious exercise.

The Court further concluded that restrictions imposed by Texas on the presence of clergy during an execution were not based on a compelling governmental interest.

Rejecting Texasโ€™s arguments

Texas argued it had two compelling governmental interests that justified its policy.

First, absolute silence was necessary in the execution chamber so they can monitor the inmateโ€™s condition through a microphone suspended overhead. Prison officials claimed that audible prayer might impede their ability to hear subtle signs of trouble or might prove distracting during an emergency.

The Court agreed that โ€œaudible prayer could present a . . . serious risk of interference during the delicate process of lethal injection. . . . But [prison officials] fail to show that a categorical ban on all audible prayer is the least restrictive means of furthering their compelling interests,โ€ as required by RLUIPA.

Second, Texas argued about concerns regarding possible disruptions. Prison officials claimed that if they allow spiritual advisors to pray aloud during executions, the opportunity โ€œcould be exploited to make a statement to the witnesses or officials, rather than the inmate. . . . [And] such statements might cause further trauma to the victimโ€™s family or otherwise interfere with the execution.โ€

The Court agreed that the government has a compelling interest in preventing disruptions of any sort and maintaining solemnity and decorum in the execution chamber. But โ€œthere is no indication in the record that Pastor Moore would cause the sorts of disruptions that [prison officials] fear.โ€

Historical practices with executions

With its decision, the Court briefly summarized the history of audible prayer at the time of execution to affirm the central importance of this practice in the Christian tradition:

As for audible prayer, there is a rich history of clerical prayer at the time of a prisonerโ€™s execution, dating back well before the founding of our Nation. For example, at Newgate Prisonโ€”one of Londonโ€™s most notorious jailsโ€”an Anglican priest would stand and pray with the condemned in their final moments. By the early 1700s, that practice had evolved to permit prisoners to be โ€œattended by a minister, or even a priest, of their own communion. Prayer at the time of execution was also commonplace in the American Colonies. . . . And during the Revolutionary War, General George Washington ordered that โ€œprisoners under sentence of deathโ€ โ€œbe attended with such Chaplains as they chooseโ€โ€”including at the time of their execution. These chaplains often spoke and prayed with the condemned during their final moments. . . . (โ€œUpon the arrival of the criminals at the place of execution, the attending chaplain . . . prayed and recommended them severally to God.โ€)

A tradition of such prayer continued throughout our Nationโ€™s history. When, for example, the Federal Government executed four members of the conspiracy that led to the assassination of President Abraham Lincoln, the prisoners were accompanied by clergy of various denominations. These โ€œspiritual advisersโ€ ministered to the condemned, and three spoke public prayers shortly before the prisoners were hanged. And in the aftermath of World War II, the United States Army even permitted Nazi war criminals facing execution to be accompanied by a chaplain, who โ€œspokeโ€ prayers on the gallows in the moments before death.

The practice continues today. In 2020 and 2021, the Federal Bureau of Prisons allowed religious advisors to speak or pray audibly with inmates during at least six federal executions. Whatโ€™s more, Texas itself appears to have long allowed prison chaplains to pray with inmates in the execution chamber, deciding to prohibit such prayer only in the last several years. (citations omitted)

What this means for churches

The ministries of chaplains carry great historical significance in the country and constitute significant and vibrant efforts still today in many parts of the country. This decision is especially relevant to chaplains carrying on that work now and going forward. Likewise, it is relevant to any church with a minister who serves as a prison chaplain, as well as churches with active prison ministries in which ministers visit prisoners, among other services.

Ramirez v. Collier, 142 S. Ct. 1264 (2021)

Richard R. Hammar is an attorney, CPA and author specializing in legal and tax issues for churches and clergy.

Key Tax Dates July 2022

File 8274 and 941 forms and meet monthly or semiweekly requirements.

Monthly requirements

If your church or organization reported withheld taxes of $50,000 or less during the most recent lookback period (for 2022 the lookback period is July 1, 2020, through June 30, 2021), then withheld payroll taxes are deposited monthly.

Monthly deposits are due by the 15th day of the following month. Note, however, that if withheld taxes are less than $2,500 at the end of any calendar quarter (March 31, June 30, September 30, or December 31), the church or organization need not deposit the taxes.

Instead, it can pay the total withheld taxes directly to the IRS with its quarterly Form 941. Withheld taxes include federal income taxes withheld from employee wages, the employeeโ€™s share of Social Security and Medicare taxes, and the employerโ€™s share of Social Security and Medicare taxes.

Semiweekly requirements

If your church or organization reported withheld taxes of more than $50,000 during the most recent lookback period (for 2022 the lookback period is July 1, 2020, through June 30, 2021), then the withheld payroll taxes are deposited semiweekly.

This means that for paydays falling on Wednesday, Thursday, or Friday, the payroll taxes must be deposited on or by the following Wednesday. For all other paydays, the payroll taxes must be deposited on the Friday following the payday.

Note further that large employers having withheld taxes of $100,000 or more at the end of any day must deposit the taxes by the next banking day. The deposit days are based on the timing of the employerโ€™s payroll. Withheld taxes include federal income taxes withheld from employee wages, the employeeโ€™s share of Social Security and Medicare taxes, and the employerโ€™s share of Social Security and Medicare taxes.

July 30, 2022: File employer exemptionโ€”Form 8274

Churches hiring their first nonminister employee between April 1 and June 29 may exempt themselves from the employerโ€™s share of Social Security and Medicare taxes by filing Form 8274 by this date (nonminister employees are thereafter treated as self-employed for Social Security purposes).

The exemption is only available to churches that are opposed on the basis of religious principles to paying the employerโ€™s share of Social Security and Medicare taxes.

July 31, 2022: File Form 941

Churches having nonminister employees (or one or more ministers who report their federal income taxes as employees and who have elected voluntary withholding) must file an employerโ€™s quarterly federal tax return (Form 941) for the second quarter of 2022 by this date. Enclose a check in the total amount of all withheld taxes (withheld income taxes, withheld Social Security and Medicare taxes paid by the employee, and the employerโ€™s share of Social Security and Medicare taxes) if less than $2,500 on June 30, 2022.

Richard R. Hammar is an attorney, CPA and author specializing in legal and tax issues for churches and clergy.

Advantage Member Exclusive

Retirement Planning for Pastors and Staff

On-Demand Webinar: Setting successful strategies as your church’s workforce ages.

Loading the player...


Editorโ€™s note. This video is part of the Advantage Membership. Learn more on how to become an Advantage Member or upgrade your membership.

In America, the retirement boom has begun. Yet statistics from annuity.org and elsewhere indicate that most Americans are not financially ready for it.

Unfortunately, this trend rings true in churches as well. But this doesn’t have to be the case. With a little forward thinking, churches can set their pastors and staff up for success during the retirement years.

In this webinar featuring CPA Elaine Sommerville, you will learn what to do–or not do–as your workforces age. Watch now to gain an overview of plans that can assist pastors and staff members with setting aside retirement funds, as well as critical considerations they must make regarding housing, spouses, health insurance and Medicare, and life insurance.

Elaine L. Sommerville is licensed as a certified public accountant by the State of Texas. She has worked in public accounting since 1985.

Key Tax Dates June 2022

Review housing allowance designations, make quarterly payments, and meet monthly or semiweekly requirements.

Monthly requirements

If your church or organization reported withheld taxes of $50,000 or less during the most recent lookback period (for 2022 the lookback period is July 1, 2020, through June 30, 2021), then withheld payroll taxes are deposited monthly.

Monthly deposits are due by the 15th day of the following month. Note, however, that if withheld taxes are less than $2,500 at the end of any calendar quarter (March 31, June 30, September 30, or December 31), the church or organization need not deposit the taxes.

Instead, it can pay the total withheld taxes directly to the IRS with its quarterly Form 941. Withheld taxes include federal income taxes withheld from employee wages, the employeeโ€™s share of Social Security and Medicare taxes (7.65 percent of wages), and the employerโ€™s share of Social Security and Medicare taxes (an additional 7.65 percent of employee wages).

Semiweekly requirements

If your church or organization reported withheld taxes of more than $50,000 during the most recent lookback period (for 2022 the lookback period is July 1, 2020, through June 30, 2021), then the withheld payroll taxes are deposited semiweekly.

This means that for paydays falling on Wednesday, Thursday, or Friday, the payroll taxes must be deposited on or by the following Wednesday. For all other paydays, the payroll taxes must be deposited on the Friday following the payday.

Note further that large employers having withheld taxes of $100,000 or more at the end of any day must deposit the taxes by the next banking day. The deposit days are based on the timing of the employerโ€™s payroll. Withheld taxes include federal income taxes withheld from employee wages, the employeeโ€™s share of Social Security and Medicare taxes (7.65 percent of wages), and the employerโ€™s share of Social Security and Medicare taxes (an additional 7.65 percent of employee wages).

June 15, 2022: Quarterly estimated tax payments for certain employees and churches

Filing for certain ministers and self-employed workers

Ministers (who have not elected voluntary withholding) and self-employed workers must file their second quarterly estimated federal tax payment for 2022 by this date. A similar rule applies in many states to payments of estimated state taxes.

Nonminister employees of churches that filed a timely Form 8274 (waiving the churchโ€™s obligation to withhold and pay FICA taxes) are treated as self-employed for Social Security, and accordingly are subject to the estimated tax deadlines with respect to their self-employment (Social Security) taxes unless they ask their employing church to withhold an additional amount of income taxes from each paycheck that will be sufficient to cover self-employment taxes (use a new Form W-4, Step 4(c), to make this request).

Payments for unrelated business income tax liability

A church must make quarterly estimated tax payments if it expects an unrelated business income tax liability for the year to be $500 or more. Use IRS Form 990-W to figure your estimated taxes. Quarterly estimated tax payments of one-fourth of the total tax liability are due by April 15, June 15, September 15, and December 15, 2022, for churches on a calendar year basis. Deposit quarterly tax payments electronically using the Electronic Federal Tax Payment System (EFTPS).

June 30, 2022: Review housing or parsonage allowance designations

Now is a good time to review the 2022 housing or parsonage allowances designated for all ministers on staff. If an allowance designated for 2022 is clearly below actual housing expenses, then the church board should consider declaring a larger portion of the ministerโ€™s remaining compensation as a housing or parsonage allowance.

A church is free to designate any portion of a ministerโ€™s compensation as a housing allowance, but remember that clergy who own their home cannot claim a housing allowance exclusion greater than the fair rental value of the home (furnished, including utilities). Therefore, the allowance ordinarily should not be significantly more than this amount.

Richard R. Hammar is an attorney, CPA and author specializing in legal and tax issues for churches and clergy.

Can Churches Assist with Medicare Premiums for Eligible Employees?

Churches must understand several rules and factors when it comes to medicare premiums for eligible employees.

Can churches assist with medicare premiums for eliglible employees?

It’s an important question as aging workers stay in the marketplace longer than in past years.

As a result, churches are facingโ€”or will faceโ€”the question of how to handle health insurance coverage for employees reaching Medicare eligibility. Upon reaching Medicare eligibility, a personโ€™s health coverage becomes a maze of options for both the employer and the employee.

Churches often desire to encourage an employee to leave a group health-care plan and enroll in Medicare to take advantage of cost savings. Many times, the employee also desires this path because it is less expensive than his or her portion of the cost of the churchโ€™s group health-care plan. When discussing Medicare as a health-care option, the topic of the churchโ€™s ability to assist with Medicare-related premiums invariably comes up.

While employers may not pay Medicare premiums directly for active employees, they may in some circumstances establish reimbursement plans for the related costs. However, employer assistance with these costs requires great caution and an understanding of multiple, little-known laws.

Navigation of this complex subject is dependent on several factors requiring skilled analysis and well-thought-out planning. The analysis is intricate and easy to misstep. The purpose of this article is to raise awareness of the rules involved and assist a church in knowing when to seek guidance from a benefits professional.

Rules to consider in the analysis

There are two primary sets of rules to consider when deciding whether to assist an employee with Medicare-related premiums and supplemental coverage.

The first is the Affordable Care Act (ACA). Created in 2010, most churches are now accustomed to navigating the ACAโ€™s intricate rules relating to health-care coverage.

The second set of rules, which is not as familiar to church employers, is the Medicare Secondary Payer (MSP) rules.

The ACA and Medicare

Medicare is not a group health-care plan under the ACA, so Medicare reimbursements or payments are considered reimbursements of an individual health insurance plan. Therefore, if a church agrees to pay an employee for Medicare premiums, it is reimbursing an individual health insurance plan. If a church has more than one employee, then the provisions of the ACA kick in, and those provisions generally prohibit the reimbursement of individual health insurance premiums.

In the past few years, two avenues have been approved that allow employers to provide for individual health insurance coverage. These avenues are specific versions of health reimbursement arrangements (HRAs): the Qualified Small Employer Health Reimbursement Arrangement (QSEHRA) or the Individual Coverage Health Reimbursement Arrangement (ICHRA).

Both HRAs have specific qualifications and operating rules. Reimbursing individual health insurance premiums outside of a qualifying HRA creates an employer-paid health plan subject to the ACAโ€™s penalty of $100 per day ($36,500 per year) per employee.

Additional ACA rules apply to employers with 50 or more full-time equivalent employees because they must offer group health insurance to all full-time employees.

Medicare Secondary Payer rules

Outside of the ACA rules, any arrangement involving Medicare and employees must also comply with the MSP rules. No one should be surprised to learn that the government does not approve of employers transferring their insurance responsibilities to the government. MSP rules define when Medicare can be the primary payer versus when the federal government insists that Medicare operate as a secondary payer behind other employer-provided insurance plans covering active employees.

For an employer with 20 or fewer full- or part-time workers that offers group health insurance plans, MSP rules allow greater latitude in working with employees eligible for Medicare. Medicare rules require an employee to enroll in Medicare when eligible and Medicare serves as the primary payer of medical needs.

But the provisions clearly state that employers of 20 or more employees may not actively encourage or compensate employees for exiting their group health plan in favor of Medicare. The employer must offer the same health-care benefits to those 65-and-older employees that they do to employees under 65. A churchโ€™s group health plan must be the primary payer and Medicare the secondary payer. While an employee may choose to exit the group health-care plan in favor of a Medicare option, the employer may not compensate or reward the employee for this decision.

Note. An employer meets the 20-or-more-employee requirement when an employer has 20 or more full-time and/or part-time employees for each working day in each of 20 or more calendar weeks in the current or preceding year.

Potential solutions

So, what are a churchโ€™s options for employees who desire to enroll in Medicare?

Churches with fewer than 20 employees that offer group health insurance

A church with fewer than 20 full- or part-time employees (as defined above)โ€”and that offers group health insurance not consisting solely of benefits excepted from the ACA rulesโ€”may take the following steps:

  • establish a group health insurance plan for employees not eligible for Medicare; and
  • create an integrated health reimbursement arrangement for those employees enrolled in Medicare Part A and Part B or D that reimburses the premiums the employee pays for Medicare Parts B and/or D only. (This is a specifically authorized method of integrating this type of HRA into an employerโ€™s group health plan.)

Churches with fewer than 50 employees not offering group insurance

A church with no more than 49 full-time equivalent employees and not offering group health insurance may consider establishing an ICHRA or a QSEHRA (see above sidebar). Both types of HRAs may reimburse individual health insurance premiums and the employeeโ€™s benefits may be used to pay for Medicare Parts B, C and/or D. However, these plans may not be limited to simply covering Medicare premiums and must comply with nondiscrimination rules.

Churches with 20 or more employees offering group insurance

For employers that offer group coverage and meet the 20-employee rule above, compliance with MSP rules is more challenging. To comply, the health-care options offered to qualifying employees and their spouses (if applicable) may not differ based on whether or not employees are eligible for Medicare. Any HRA must comply with ACA rules. The interplay of these rules makes it difficultโ€”if not impossibleโ€”to create a plan providing for the reimbursement of Medicare-related premiums for active employees.

Employer size is the determining factor

In summary, an employee may enroll in Medicare when he or she becomes eligible and may still participate in his or her employerโ€™s group health planโ€”or choose to leave the employerโ€™s plan.

However, the size of the employer determines which plan provides primary coverage for health expenses and which one provides secondary coverage, and it determines the options available (or not) for the employer to reimburse costs.

Assisting employees with Medicare-related premiums should only be undertaken when a church has actively sought the assistance of a benefits professional skilled in working with these specific rules. Churches and employees may also find assistance through a State Health Insurance Assistance Program (SHIP) that provides free health insurance counseling services. Locate a local SHIP by visiting shiphelp.org or by calling (toll-free) 1-800-633-4227.

Elaine L. Sommerville is licensed as a certified public accountant by the State of Texas. She has worked in public accounting since 1985.

RECOMMENDED READING

Politics and the Church: Activism, Speech, and the Tax Code

Sometimes, the lines blur between politics and the church. This recommended reading – and viewing – list can help.

Sometimes, the lines blur between politics and the church to the point that church leaders can wonder what types of political activities and political speech are allowed under section 501(c)(3) of the tax code.

It’s a question we often receive because of the federal tax-exempt status that churches automatically receive under section 508 of the Internal Revenue Code.

This recommended, carefully-curated members-only reading list, devoted to politics and the church, lays out the doโ€™s and donโ€™ts as described in section 501(c)(3), as well as relevant IRS rulings and court decisions.


Lead Your Church With Confidence – Become a Church Law & Tax Member Today.


The list includes a thought piece on whether your church should get political at all, along with a series of analysis pieces on the tax implications of getting political in the first place.

All are were created in partnership with experts whose hearts are geared to inform church leaders who, in turn, must weigh how God is calling them to speak into elections and other political matters.


Downloadable Checklist: How Various Political Activities Might Affect Your Church’s Tax-Exempt Status

Which political activities may affect your church’s tax-exempt status, based on IRS guidance.

Last Reviewed: April 25, 2024

Election years frequently prompt a common question among church leaders and pastors: What types of political activities and speech are allowed under section 501(c)(3) of the tax code?

While political activities and speech by churches and pastors are protected by the US Constitutionโ€™s First Amendment, the Internal Revenue Code contains specific language that either prohibits or limits certain activities conducted by tax-exempt entities. Violations can lead to excise taxes, the revocation of federal tax exemption, or both. While few public examples exist of the enforcement of these rules over the years by the Internal Revenue Service (IRS), churches and church leaders still should understand the prohibitions and limitations, including any potential tax consequences any violations may trigger.

This chart provides a variety of examples of political activities churches might wish to do and briefly details the related IRS guidance, including the potential effects of those activities on a churchโ€™s tax-exempt status. The goal is to provide a quick reference for church leaders that helps them make informed decisions.

To go deeper on these issues, donโ€™t miss โ€œThe Tax Implications of Churches and Political Involvement,โ€ by attorney, CPA, and senior editor Richard R. Hammar, and โ€œChurches, Politics, and Constitutional Protections,โ€ by attorney Erik Stanley.

ACTIVITY

IMPACT ON TAX- EXEMPT STATUS

BASIS

A church makes contributions to a candidateโ€™s campaign fund

Prohibited

IRS Publication 1828

A church makes public statements of position (verbal and written) in favor of or in opposition to candidates for office through official church publications, at official church functions, or both

Prohibited

IRS Publication 1828

A churchโ€™s pastor delivers a sermon series addressing what the Bible says about abortion, criminal justice reform, sexual orientation and gender identity, and other topics with social and spiritual implications

Permitted

First Amendment of the US Constitution

A church provides a nonpartisan forum for all candidates to address the church

Permitted

IRS Publication 1828

A church invites all candidates for a political office to address the congregation and informs the congregation before each candidateโ€™s speech that the views expressed are those of the candidate and not the church, and that the church does not endorse any candidate

Permitted

Revenue Ruling 74-574; IRS Publication 1828

A church invites only one candidate in a political campaign to address the congregation

Prohibited

Revenue Ruling 2007-41; IRS Publication 1828

A church provides an opportunity for a candidate to speak in a noncandidate capacity (for example, as a member of the church, public figure, or expert in a nonpolitical field) without providing equal access to all political candidates for the same office. The church ensures that the candidate speaks in a noncandidate capacity; no reference is made to the personโ€™s candidacy; the church mentions the capacity in which the candidate is appearing (without mentioning the personโ€™s political candidacy); and no campaign activity occurs.

Permitted

IRS Publication 1828

A church distributes a compilation of voting records of all members of US Congress on major legislative issues involving a wide range of subjects; the publication contains no editorial opinion, and its text, design elements, and structure do not imply approval or disapproval of any members or their voting records

Permitted

Revenue Ruling 78-248; IRS Publication 1828

A church distributes a voter guide containing questions answered by all candidates. The questions cover a wide range of topics, but the wording of the questions demonstrates bias on certain issues.

Prohibited

Revenue Ruling 78-248; IRS Publication 1828

A church endorses a candidate (by any variety of ways, including verbal or written statements, references to the candidateโ€™s political party, references to the candidateโ€™s distinctive platform or biography, and/or showing the candidateโ€™s picture)

Prohibited

Int. Rev. News Release IR-96-23; IRS Publication 1828

Church employees carry on campaign activities for a candidate within the context of their church employment

Prohibited

FSA 1993-0921-1; IRS Publication 1828

A church fails to โ€œdisavowโ€ the campaign activities of persons under โ€œapparent authorizationโ€ from the church by repudiating those acts โ€œin a timely manner equal to the original actionsโ€ and taking steps โ€œto ensure that such unauthorized actions do not recurโ€

Prohibited

FSA 1993-0921-1

A church engages in fundraising on behalf of a candidate

Prohibited

Int. Rev. News Release IR-96-23; IRS Publication 1828

A church conducts a neutral voter registration drive

Permitted

11 C.F.R. ยง 111.4(c)(4); IRS Publication 1828

A church buys and places newspaper ads urging voters to vote for or against a candidate

Prohibited

Branch Ministries, Inc. v. Commissioner, 99-1 USTC ยถ50,410 (D.D.C. 1999), affโ€™d, Branch Ministries v. Rossotti, 2000 USTC ยถ50,459 (D.C. Cir. 2000)

A church website contains information either supporting or opposing candidates for public office

Prohibited

IRS Publication 1828

A church website contains links to candidate-related materials, and does not include any text, design elements, or structure indicating support of or opposition to any of the candidates

Permitted

Revenue Ruling 2007-41; IRS Publication 1828

A church website links to third-party websites containing materials supporting or opposing candidates

Prohibited

IRS Publication 1828

A minister who is known well in the community attends a press conference at a political candidateโ€™s campaign headquarters and states that the candidate should be reelected. The minister does not say he is speaking on behalf of his church. His endorsement is reported on the front page of the local newspaper, and he is identified in the article as the minister of his church.

Permitted

Revenue Ruling 2007-41; IRS Publication 1828

A church maintains a website that includes biographies of its ministers, times of services, details of community outreach programs, and activities of members of its congregation. A member of the congregation is running for a seat on the town council. Shortly before the election, the church posts the following message on its website: โ€œLend your support to your fellow parishioner in Tuesdayโ€™s election for town council.โ€

Prohibited

Revenue Ruling 2007-41; IRS Publication 1828

A church urges its members to contact members of the state legislature and urge them to reject a proposed bill legalizing marijuana

Prohibited

IRS Publication 1828

A church provides its members with educational materials about the legalization of marijuana and hosts an educational meeting on the topic

Permitted

IRS Publication 1828

A church gives a pro-life advocacy group permission to place pamphlets on vehicles in the churchโ€™s parking lot during Sunday worship services. The pamphlets urge congregants to support a โ€œpro-lifeโ€ slate in the upcoming election.

Unclear based on IRS regulations and current lawโ€”but likely prohibited

A church owns space suitable for events and makes it available for rent to the public on a first come, first served basis. A candidate pays the standard fee to host a campaign dinner.

Permitted

IRS Publication 1828

A church sets up a booth at the state fair where citizens can register to vote. The booth only contains the churchโ€™s name, the date of the next statewide election, and notice of the opportunity to register. No reference to any candidate or political party is made in any materials or in any statements given by volunteers.

Permitted

IRS Publication 1828

A church maintains a list containing contact information for its members and has never rented it to a third party. The church allows one candidate to rent the list to send campaign information, but declines similar requests from other candidates.

Prohibited

IRS Publication 1828

A church sets up a telephone bank to conduct a โ€œget-out-the-voteโ€ effort and contacts registered voters in its district. Church volunteers are instructed to ask the registered voters about their positions on certain moral issues, and if the voterโ€™s positions align with a specific candidate running for office in the district, to then remind them about the upcoming election, the importance of voting, and the availability of church-sponsored transportation to the polls.

Prohibited

IRS Publication 1828

For a more detailed discussion about political activities and the church, visit ChurchLawAndTax.comโ€™s Recommended Reading page, โ€œChurches and Political Activities,โ€ as well as chapter 12 of Richard R. Hammarโ€™s annual Church & Clergy Tax Guide.

The Tax Implications of Churches and Political Involvement

The tax implications for churches that engage in political campaigns and legislative lobbying.

Last Reviewed: July 27, 2026

To maintain federal tax-exempt status under section 501(c)(3) of the Internal Revenue Code, churches must follow specific rules. Two key restrictions apply:

  • No political campaign activityโ€”churches may not support or oppose any candidate for public office.
  • Limited lobbyingโ€”churches may not devote a substantial part of their activity to influencing legislation.

While enforcement has historically been limited, violations can carry significant tax consequences. Church leaders should understand these restrictions and evaluate how their activities may be affected.


Historical Context: A Tradition of Political Engagement

Political involvement by churches and clergy is nothing new. Common examples include:

  • Inviting candidates to speak at services
  • Distributing voter guides or candidate literature
  • Organizing voter registration drives
  • Recruiting volunteers for campaigns
  • Making statements for or against political candidates during worship

However, even well-intentioned actions can risk a churchโ€™s tax-exempt status.


What Section 501(c)(3) Requires

According to the law, a church is tax-exempt only if:

โ€œNo substantial part of the activities of which is carrying on propaganda, or otherwise attempting to influence legislation, and which does not participate in, or intervene in โ€ฆ any political campaign on behalf of any candidate for public office.โ€

This means:

  • No substantial lobbying (even if not related to elections)
  • No political campaign activity whatsoever, even if minimal

These activities arenโ€™t illegalโ€”but they can result in loss of tax-exempt status.

An IRS statement included with the 2025 settlement of a lawsuit brought by two churches and the National Religious Broadcasters signaled the agency may grant more latitude to churches with respect to political campaigns involving candidates.

However, a federal judge dismissed the case on jurisdictional grounds, leaving things status quo.


IRS Enforcement: Rare but Real

Although violations have occurred with little IRS response, there have been some notable actions:

  • 1990s: The IRS revoked a New York churchโ€™s exemption for engaging in a presidential campaign through full-page newspaper advertisements. The decision was affirmed on appeal.
  • Jimmy Swaggart Ministries (1992): Agreed to cease political activity after IRS findings.
  • 2004 Ruling: A pastorโ€™s comments opposing candidates were imputed to the church. The IRS imposed a tax but did not revoke status.

Limited enforcement is partly due to the Church Audit Procedures Act, which restricts when and how the IRS can investigate churches. A 2009 federal court ruling further limited IRS authorityโ€”though a later settlement in 2014 affirmed the IRS still had enforcement procedures in place.


Understanding Political Campaign Activity

What the Tax Code Prohibits

Churches cannot:

  • Make statements (oral or written) supporting or opposing candidates
  • Distribute biased voter guides
  • Allow use of church property or events to promote candidates

This includes all levels of government: local, state, and national.

What the IRS Says (Publication 1828)

The IRS allows personal political activity by church leaders, but not during:

  • Official church functions
  • Church publications
  • Any event where the leader represents the church

To protect the church, leaders should clarify when theyโ€™re speaking personallyโ€”not on behalf of the church.


Candidates Speaking at Church

Speaking as a Candidate

Churches may invite candidates to speakโ€”but must ensure:

  • Equal opportunity is given to all candidates
  • The church does not endorse or oppose the candidate
  • No fundraising occurs
  • The nonpartisan purpose of the visit is clear
  • The church maintains a neutral tone in all announcements

Speaking as a Noncandidate

Candidates may also speak in a noncandidate capacity (e.g., as a public figure or expert). In these cases:

  • The event must remain nonpartisan
  • No mention of candidacy or elections is permitted
  • The individual must be invited for reasons unrelated to the campaign

Hosting Forums or Debates

Public candidate forums are allowedโ€”but only if they are neutral. The IRS evaluates:

  • Who prepares and asks the questions
  • Whether issues reflect public interest
  • Whether all candidates get equal opportunity
  • Whether the event avoids endorsements or disapproval
  • Moderator neutrality

Voter Education and Registration

Churches may conduct:

  • Voter registration drives
  • Distribute nonpartisan voter guides
  • Host educational events

But they must avoid:

  • Comparing candidate views to the churchโ€™s positions
  • Distributing guides with biased design, content, or placement
  • Omitting candidates or editorializing their views

Even third-party guides may count as political activity if biased and distributed by the church.


Campaign Literature on Church Property

If individuals distribute campaign materials on church premisesโ€”especially with leadershipโ€™s permissionโ€”the church risks appearing to endorse a candidate.

Key point: If church leaders allow this, the IRS may view it as indirect campaign participation.

Unsolicited pamphleteering (e.g., flyers on windshields without church knowledge) is not a violationโ€”unless church leaders gave permission.


Business Activities and Campaigns

Churches must be cautious with:

  • Renting out space
  • Selling mailing lists
  • Accepting political advertising

IRS will consider:

  • Equal access for all candidates
  • Whether services are offered to the general public
  • Standard pricing practices
  • Whether the church routinely conducts the activity

Church Websites and Digital Content

The IRS treats websites like printed materials. Churches are responsible for:

  • Content favoring or opposing candidates
  • Links to outside political websites
  • Context in which links or statements are shared

Churches should regularly review links and online materials during election seasons.


Lobbying Restrictions

Churches may lose tax-exempt status if a substantial part of their activity is lobbying. This includes:

  • Urging the public to contact legislators
  • Supporting or opposing legislation
  • Advocating for ballot measures

What Isnโ€™t Lobbying?

  • Educating the public on policy issues
  • Hosting educational meetings
  • Distributing materials in an educational, nonpartisan way

How Much Is Too Much?

There is no clear IRS rule defining โ€œsubstantial.โ€ Courts have offered guidance:

  • Less than 5% of a churchโ€™s time/resources may be considered insubstantial (Seasongood v. Commissioner, 1955)
  • 16% to 20% was deemed substantial in another case (Haswell v. U.S., 1974)

The IRS considers all facts, including:

  • Time spent by staff and volunteers
  • Resources and money used for lobbying

Consequences for Violations

Political Campaign Violations

Possible penalties include:

  • Loss of tax-exempt status
  • Loss of tax-deductible contributions
  • Excise taxes, such as:
    • 10% on the churchโ€™s political spending
    • 2.5% on responsible managers (up to $5,000)
    • Additional taxes (up to 100%) if not corrected
    • 50% on managers who refuse to correct (up to $10,000)

Correction involves recovering the funds and creating safeguards to prevent future violations.

Lobbying Violations

Excessive lobbying may lead to:

  • Loss of tax-exempt status
  • Federal and state taxes on all income
  • Potential excise taxes on political expenditures (though churches are often excluded)

What Losing Tax-Exempt Status Means

If a church loses its status:

  • Income becomes taxable
  • Donors lose their charitable deduction

The church may lose:

  • Property tax and sales tax exemptions
  • Exemption from unemployment tax
  • Eligibility for 403(b) retirement plans
  • Preferential mailing rates
  • Protection under the Church Audit Procedures Act
  • Exemption from religious discrimination claims in certain cases

These consequences are seriousโ€”and should be carefully considered when evaluating political involvement.

Matthew Branaugh, attorney and editor for ChurchLawAndTax.com, contributed to this article.
Richard R. Hammar is an attorney, CPA and author specializing in legal and tax issues for churches and clergy.

Politics, Churches, and Constitutional Protections

The Johnson Amendment and other tax laws try to limit activities by churches that intersect with politicsโ€”but certain constitutional protections allow more engagement than some realize.

Last Reviewed: July 27, 2026

Every election year, churches question what they can do or say about the upcoming election.

Quite often, the central question is this: How far is too far?

Many churches earnestly attempt to navigate this dilemma while others are simply silent.

As a pastor or church leader, do you know what your church may legally do during an election year? Or would you wonder if you really understood what the law says and how it applies to your church?

Unfortunately, articles and guides about the Internal Revenue Service (IRS) regulations on election-year activities by churches often overlook the US Constitution and its safeguards of the free exercise of religion, freedom of speech, and protection from government intrusion into the church.

Your churchโ€™s ability and freedom to address an election are broad, even under current tax law. This is especially true considering the constitutional guarantees churches enjoy.

Confusionโ€”and more confusion

Much of the confusion stems from the Johnson Amendment, a controversial provision of the federal Internal Revenue Code (IRC) since its adoption in the 1950s. It prohibits tax-exempt entities from opposing or endorsing political candidates. The provision also significantly restricts their lobbying and advocacy efforts tied to legislative matters and ballot measures.

Adding to the confusion are recent efforts to undo the Johnson Amendment. President Donald Trump attempted to eliminate it through a 2018 Executive Order, although the move lacked any substantive legal effect.

Separately, a 2024 legal challenge brought through a federal case in Texas also challenged the Johnson Amendment. But an attempted settlement in 2025 with the Internal Revenue Service (IRS)โ€”one that would have involved language granting churches and religious organizations more leeway with political activitiesโ€”proved unsuccessful after the judge dismissed the matter on procedural grounds.

Why did the Johnson Amendment happen?

The Johnson Amendment restricts a tax-exempt organizationโ€™s interactions with candidates and elections. The Amendment gets its name from Senator Lyndon Johnson. He was the motivating factor in adding the provision to the tax code in 1954.

The history of the Amendment suggests that Johnson wanted to silence two powerful, secular nonprofit organizations. The organizations were opposing his reelection to the US Senate because they believed he was soft on communism.

The Amendment was part of a massive tax overhaul bill and was inserted into the bill by a voice vote.

There were no debates or committee hearings. There was no meaningful consideration of how the Amendment would impact the constitutional rights of churches.

President Eisenhower signed the tax bill, which included the Johnson Amendment, into law without comment in August 1954. Since that time, the Johnson Amendment has been part of federal tax law.

The Johnson Amendment is the last sentence of section 501(c)(3) of the IRC. It states that nonprofit organizations may not โ€œparticipate in, or intervene in (including the publishing or distributing of statements), any political campaign on behalf of (or in opposition to) any candidate for public office.โ€ Section 501(c)(3), of course, applies to churches.

How is the Johnson Amendment enforced?

The IRS enforces the Johnson Amendment along with the rest of the tax code. Its record of enforcement since 1954 has been spotty and uneven. For example, on its website, the IRS states that nonprofit organizations are โ€œabsolutely prohibited from directly or indirectlyโ€ violating the Johnson Amendment. Yet there is no explanation of what an โ€œindirectโ€ violation of the Johnson Amendment is or could be.

The Johnson Amendment itself prohibits a church from โ€œparticipating inโ€ a candidateโ€™s campaign. However, the law contains no clear definition of what โ€œparticipationโ€ consists of.

Despite this vagueness, the IRS warns that a violation of the Johnson Amendment โ€œmay result in denial or revocation of tax-exempt status and the imposition of certain excise taxes.โ€

The predictable result of the inherent vagueness and murkey enforcement rules is to chill the speech of Americaโ€™s churches and pastors.

Pastors often admit they don’t know what is considered prohibited speech when it comes to candidates and elections.

So, most just say nothing. Only an intrepid few may decide to shoot in the dark and hope for the best.

This only magnifies the problem. Pastors are frequently intimidated because they do not know what the IRS thinks they can or cannot say.

This chill on speech is further exacerbated by the fact that churches cannot just sue the IRS to have the Johnson Amendment declared unconstitutional. The rules of federal court jurisdiction (when a lawsuit may be brought to court) prohibit lawsuits against the IRS until a provision of the tax code has been enforced against a taxpayer and a penalty has been levied and upheld during an internal IRS appeal process.

The IRS decides when to go to court

The result is that the IRS decides how, when, and with whom it will get into a lawsuit with. For decades, the IRS studiously avoided a lawsuit over the constitutionality of the Johnson Amendment. When two Texas churches and the National Religious Broadcasters sued in August of 2024, it marked the first time the agency engaged such litigation.

With the federal judge’s dismissal of the Texas case, though, no court still has confronted the constitutionality of government regulation of a churchโ€™s political speech during a church service or event.

Yet this is precisely what the Johnson Amendment claims authority to do. The status quo perpetuates the law. As a result, most churches simply self-censor.

Moreover, some organizations that advocate for radical enforcement of the โ€œseparation of church and stateโ€ take advantage the amendment’s vagueness.

One organization even conducted a nationwide advocacy campaign where it asked its supporters to turn in churches to the IRS.

Never mind that its view of the Johnson Amendment was so extreme the IRS wouldn’t act on the complaints.

Just the threat of a complaint or an actual complaint followed by a press release further chilled free speech.

Is the Johnson Amendment constitutional?

Numerous legal scholars have written law review articles arguing that the Johnson Amendment is unconstitutional. These arguments focus on the Establishment, the Free Exercise, and the Free Speech Clauses of the First Amendment to the US Constitution.

What follows is a summary of some of the legal arguments for how the Johnson Amendment appears to violate each clause.

The Establishment Clause

The Establishment Clause prohibits excessive entanglement of the government with religion. The IRS cannot enforce the Johnson Amendment without an IRS agent parsing the speech of a church or a pastorโ€™s sermon or other speech to determine if it crossed the line into a Johnson Amendment violation.

The US Supreme Court has heldโ€”in more than one caseโ€”that a law that requires pervasive government surveillance and monitoring of religion results in excessive entanglement of the government with religion.

Put simply, the government cannot enforce the Johnson Amendment without intruding into the internal activities and speech of a church. Such enforcement of the Johnson Amendment would unconstitutionally entangle the government with religion.

The Free Speech Clause

The Free Speech Clause prohibits โ€œcontent-basedโ€ restrictions on speech. This kind of restriction is one where the government must review the content of speech to determine if it violates the law.

In cases like this, courts hold the government to the highest constitutional standard in order to justify why it needs to review the content of speech.

The Johnson Amendment certainly requires the IRS to review the content of a churchโ€™s speech. In fact, there is no way to enforce the Johnson Amendment without reviewing the content of a churchโ€™s speech. This content review, coupled with the vagueness of the Johnson Amendmentโ€™s text, gives the government broad censorship power to prohibit speech.

Content-based restrictions on speech are highly disfavored. In fact, they are usually unconstitutional because these kinds of restrictions give the government far too much censorship power.

The Free Speech Clause also prohibits a speech restriction that creates an unconstitutional condition. Stated simply, the Johnson Amendment forces churches to give up their speech rights in order to retain their tax-exempt statuses. This is despite the fact that the Constitution (by virtue of the First Amendmentโ€™s Establishment Clause) requires the government to exempt a church from taxation.

Another way of looking at it

Would it be okay for the government to tell churches that they can retain their tax-exempt statuses only if they provide free housing for military troops (barred by the Third Amendment)? What about if they allow the police to search their buildings without warrants (barred by the Fourth Amendment)? Those kinds of restrictions would be instantly condemnedโ€”and rightly soโ€”as unconstitutional. Yet the Johnson Amendment says churches can retain their tax-exempt statuses only if churches forfeit their First Amendment rights of speech. This is an unconstitutional trade-off.

The Free Speech Clause also prohibits vague restrictions on speech. The reason is that vague restrictions may result in self-censorship and a chill on speech. As we have already discussed, the Johnson Amendment is full of the type of vagueness to create such a chill.

The Free Exercise Clause

The Johnson Amendment also violates the Free Exercise Clause.

This is because it expressly discriminates against religious speech and penalizes such speech with civil or criminal penalties.

Why hasnโ€™t the Johnson Amendment been declared unconstitutional?

Given the serious constitutional violations inherent in the Johnson Amendment, why has it not been declared unconstitutional? The answer lies in the continued status quo.

Again, most churches self-censor, thereby doing the IRSโ€™s enforcement job for it. The few churches investigated for Johnson Amendment violations have generally settled with the IRS. They did so to avoid draconian tax penalties and consequences.

But outside of those few examples, the IRS has essentially avoided direct enforcement action against churches.

The status quo fosters self-censorship by churches and a chill on speech. Enforcement of the Johnson Amendment comes from churches enforcing the law against themselves.

What should happen with the Johnson Amendment?

The status quo is a burden on the constitutional rights of Americaโ€™s churches and pastors. In the absence of a court challenge to the Johnson Amendment, what should happen with the law?

Some have argued that getting rid of the Johnson Amendment would turn churches into pawns of the political parties. Yet the church does not need the government to protect it against itself. We should not allow an unconstitutional law to remain out of a misguided motivation to protect the theological purity of the church. That is not the governmentโ€™s job anyway.

Others have argued that getting rid of the Johnson Amendment would allow churches to funnel โ€œdark moneyโ€ to political candidates, campaigns, and parties. Yet the Johnson Amendment applies to far more than just money.

Allowing an unconstitutional speech restriction that entangles the government with religion as a means of preventing political contributions by churches is overbroad. The simple answer is to prohibit political contributions by churches. Congress attempted to do just that when it introduced the Free Speech Fairness Act. The Act would have amended the Johnson Amendment to prohibit political contributions but remove the unconstitutional speech restrictions. The effort stalled, though, and has not moved forward to date.

The answer is not to jettison the Johnson Amendment entirely. Let’s instead remove provisions that prohibit the free speech and free exercise rights of Americaโ€™s churches and pastors. Perhaps such an amendment will become politically viable in the future.

What about ballot initiatives and legislation?

In addition to the Johnson Amendment, section 501(c)(3) of the Tax Code also includes a limitation on legislative activities by tax-exempt organizations. This section was added to the tax code in 1934. It states that โ€œno substantial part of the activities of which is carrying on propaganda, or otherwise attempting, to influence legislation.โ€ This restriction applies to activities that support or oppose pieces of legislation, such as bills and ballot initiatives.

The lobbying restriction was sponsored by Sen. David Reed. Reed was a Republican from Pennsylvania who wanted to silence a nonprofit organization, the National Economy League. The League was in direct conflict with Sen. Reed over the issue of benefits to veterans. The National Economy League was lobbying against a bill introduced by Sen. Reed who had made the issue, and his bill, the centerpiece of his reelection campaign to the US Senate.

Unlike the Johnson Amendment, the restriction on legislation is not an absolute prohibition, but just a limitation. The IRS does not define what an insubstantial amount of legislative activity is, but some guidance suggests that more than 5 percent to 15 percent of a churchโ€™s overall activities might be considered substantial.

Churches are allowed to directly support or oppose legislation, encourage congregations to vote for or against proposed laws, and speak into broader matters of public policy. None of these activities come close to the legislative limit included in section 501(c)(3).

What should churches do when it comes to an election?

Unless or until Congress amends the Johnson Amendment or a court declares it to be unconstitutional, it is still law. And the law regarding lobbying about legislation remains in place. When it comes to interacting with elections and candidates, churches should consider the following.

Recognize the significant and underappreciated constitutional protections churches have

Church leaders may be surprised by how much their churches may do in an election year. There are valuable resources that will help to cut through some of the vagueness and provide a roadmap as to what is permissible under current law. Thatโ€™s true with respect to candidates for political office, as discussed above. Thatโ€™s also true with respect to lobbying efforts related to legislative matters and ballot measures, as also discussed above.

Additionally, there are numerous activities that fall well within the bounds of current IRS guidance and tax law that churches also should contemplate. Such activities range from public forums inviting all candidates to speak, to compilations of voting records (absent editorial comment or approvals/disapprovals of those records), to neutral voter registration drives.

Even though the Johnson Amendment is unconstitutional, churches should appreciate the vast constitutional protections they currently enjoy without threat of losing their tax-exempt statuses. Doing so can help you avoid self-censorship and feel confident that there is a great deal your church may do should its leaders feel called to do so. Moreover, there are legal groups waiting and ready to provide pro-bono representation in the event a legal challenge ever arises.

Each church must decide for itself how to address politics and elections

For far too long, the Johnson Amendment and IRS guidance has made this kind of decision a legal decision, instead of a theological decision. The fact that this is true should be concerning.

Not every church will be called by its theology to speak about an election or candidates, but some will. Pastors and churches know their congregations best. Every church should have the choice to decide what to do for itself, not out of fear of violating the law, but out of its convictions informed by its theology.

Erik Stanley is a law professor at Liberty University School of Law and an attorney at Provident Law, specializing in religious liberties, churches and nonprofits, commercial litigation, and business law. He is a former editorial advisor for Church Law & Tax.

Key Tax Dates for May 2022

Along with monthly and semiweekly requirements, note quarterly filing and forms pertinent to your church or ministry.

Monthly requirements

If your church or organization reported withheld taxes of $50,000 or less during the most recent lookback period (for 2022 the lookback period is July 1, 2020, through June 30, 2021), then withheld payroll taxes are deposited monthly.

<img class=”alignleft size-thumbnail wp-image-52069″ src=”https://www.churchlawandtax.com/wp-content/uploads/sites/2/2023/04/128783.webp?w=150&h=150&crop=1″ alt=”” width=”150″ height=”150

Monthly deposits are due by the 15th day of the following month. Note, however, that if withheld taxes are less than $2,500 at the end of any calendar quarter (March 31, June 30, September 30, or December 31), the church or organization need not deposit the taxes.

Instead, it can pay the total withheld taxes directly to the IRS with its quarterly Form 941. Withheld taxes include federal income taxes withheld from employee wages, the employeeโ€™s share of Social Security and Medicare taxes (7.65 percent of wages), and the employerโ€™s share of Social Security and Medicare taxes (an additional 7.65 percent of employee wages).

Semiweekly requirements

If your church or organization reported withheld taxes of more than $50,000 during the most recent lookback period (for 2022 the lookback period is July 1, 2020, through June 30, 2021), then the withheld payroll taxes are deposited semiweekly.

This means that for paydays falling on Wednesday, Thursday, or Friday, the payroll taxes must be deposited on or by the following Wednesday. For all other paydays, the payroll taxes must be deposited on the Friday following the payday.

Note further that large employers having withheld taxes of $100,000 or more at the end of any day must deposit the taxes by the next banking day. The deposit days are based on the timing of the employerโ€™s payroll. Withheld taxes include federal income taxes withheld from employee wages, the employeeโ€™s share of Social Security and Medicare taxes (7.65 percent of wages), and the employerโ€™s share of Social Security and Medicare taxes (an additional 7.65 percent of employee wages).

May 10, 2022: Employerโ€™s quarterly federal tax returnโ€”Form 941

Churches having nonminister employees (or one or more ministers who report their federal income taxes as employees and who have elected voluntary withholding) may file their employerโ€™s quarterly federal tax return (Form 941) by this date instead of April 30 if all taxes for the first calendar quarter have been deposited in full and on time.

May 16, 2022: File forms 990, 990-T, and 5578

Information returnโ€”Form 990

An annual information return (Form 990) for tax-exempt organizations is due by this date for tax year 2021. Form 990 summarizes revenue, expenses, and services rendered. Organizations exempt from federal income tax under section 501(c)(3) of the Internal Revenue Code must report additional information on Schedule A.

Note. Churches, conventions and associations of churches, โ€œintegrated auxiliariesโ€ of churches, and church-affiliated elementary and secondary schools are among the organizations that are exempt from this reporting requirement. Organizations not exempt from this reporting requirement must file the Form 990 if they normally have annual gross receipts of $50,000 or more.

Unrelated business income tax returnโ€”Form 990-T

An unrelated business income tax return (Form 990-T) must be filed by this date by churches and any other organization exempt from federal income tax that had gross income from an unrelated trade or business of $1,000 or more in 2021.

Certificate of racial nondiscriminationโ€”Form 5578

Annual certification (for calendar year 2021) of racial nondiscrimination by a private school exempt from federal income tax (Form 5578) must be filed by this date by schools that operate on a calendar-year basis.

Fiscal year schools must file the form by the 15th day of the fifth month following the end of their fiscal year. This form must be filed by preschools, primary and secondary schools, and colleges, whether operated as a separate legal entity or by a church.

If an organization is required to file Form 990 (Return of Organization Exempt From Income Tax), or Form 990-EZ (Short Form Return of Organization Exempt From Income Tax), the certification must be made on Schedule E (Form 990 or 990-EZ), Schools, rather than on this form.

Advantage Member Exclusive

Lessons From Mars Hill: Who Pilots Your Church?

On-Demand Webinar: Why quiet governance changes run the risk of eroding congregational trust.

Loading the player...


Editorโ€™s Note. This video is part of the Advantage Membership. Learn more on how to become an Advantage Member or upgrade your membership.

In recent years, a growing number of churches have contemplated changing the governance structures contained in their bylaws. For practical reasons, these changes have often moved those structures from ones where voting rights for key decisions reside with members of the congregation to ones where that authority exclusively rests in the hands of a group of elders or the church’s board. To some church leaders, the changes make sense because they can reduce burdens and create efficiencies. But as Christianity Today’s podcast The Rise and Fall of Mars Hill powerfully demonstrates, significant problems can arise in a church when a move to consolidate decision-making power occurs with little or no warning to the church’s members.

In this exclusive webinar for Advantage Members, attorney Erika Cole dives deeply into this trend, examining the roles and purposes of governance, the reasons some churches consider changes, and why leadership must exercise great caution and transparency before ever proceeding with one.

You can download the presentation slides here.

More on this topic:

Find out more on this topic in Erika Coles article, The Dangers of a Quiet Governance Change.

Erika E. Cole, Esq., known as The Church Attorneyยฎ, is one of only a handful of attorneys in the nation who practices exclusively in the area of church law. She currently serves as a senior editorial advisor for Christianity Todayโ€™s ChurchLawAndTax.com.

The Dangers of a Quiet Governance Change

Subtly shifting who has authority to make key decisions in your church may make senseโ€”but may also erode congregational trust.

In recent years, and without much fanfare, many churches have quietly shifted their governance structures, moving from structures where voting rights for key decisions reside with members of the congregation to structures where that authority exclusively rests in the hands of a group of elders or the churchโ€™s board.

To church leadership, the shift may make sense on paper, reducing burdens and creating efficiencies. But making such a shift also threatens to erode the trust of a congregation if it is done for the wrong reasons, or if it is done for good reasons, but mishandled. When such a significant change goes awryโ€”as has been witnessed at a handful of high-profile churchesโ€”the consequences can be devastating.

Christianity Todayโ€™s podcast The Rise and Fall of Mars Hill powerfully demonstrates the trouble that can arise in a church when decision-making power gets consolidated.

Situations like this one offer an important caution: Church leaders are wise to review and understand their churchโ€™s governance model, and why it exists, before making plans to change it. And if they choose to pursue a change, leaders must carefully contemplate how to communicate with their congregations to demonstrate transparency and integrity throughout that process.

What is church governance?

The word โ€œgovernanceโ€ comes from a Greek word meaning โ€œto pilotโ€ or โ€œto steer.โ€ In the context of church operations, governance connotes who has decision-making authority in significant matters such as buying or selling church property, adopting the annual budget, the approval of a merger or acquisition, and the hiring or firing of key leaders.

A churchโ€™s governance structure most commonly gets set at the time the church is founded. How it gets set depends on several factors, including denominational affiliations.

The role of bylaws

Many churches incorporate at their founding. Whether incorporated or not, nearly all adopt governing documents known as bylaws. These documents define the systems and processes for decision-making and leadership within the church.

Common Church Governance Models

Church bylaws typically reflect one of these models:

  • Board-led church: A governing board (e.g., elders, trustees, directors) acts on behalf of the congregation. The board makes operational decisions without congregational involvement, unless required by state law.
  • Congregation-led church: Members vote on major decisions, as outlined in the bylaws. This model encourages broad participation and transparency.
  • Denomination-led church: A hierarchical structure, governed by a Book of Discipline or similar document. Local churches operate under the oversight and guidelines of the denomination.

A Healthy Governance Ecosystem

A strong governance model often includes:

  1. Pastoral leadership
  2. A governing board (elders, trustees, directors)
  3. The congregation

All three components can coexist across different governance models.

Shifting Governance Trends

After more than 20 years representing churches, I’ve reviewed hundreds of bylaws. While the congregation-led model remains common, many churches are now shifting toward board- or elder-led models that consolidate decision-making.

This shift often occurs through bylaw revisions, reducing or eliminating the congregation’s decision-making role. When one part of the governance ecosystem is removed, problems frequently arise.

The Role of Church Members

Church members are often the lifeblood of a congregation. Removing their voice from decisions can cause confusion and distrust.

A Personal Example

I grew up in a rural church with fewer than 200 members. These members:

  • Maintained the building
  • Provided music and administrationโ€”unpaid
  • Shared meals and supported one another

Quarterly business meetings allowed members to vote on everything from budgets to special events. Membership came through baptism and fellowship. Members were deeply invested in church operations.

When a congregation-led church changes its structure suddenly, members can feel blindsided.

Why Churches Shift Away from Congregation-Led Models

Church leaders may choose to move away from congregation-led structures for reasons like:

  • Avoiding conflict: To reduce tension during contentious meetings.
  • Increasing efficiency: To streamline decisions without red tape.

However, fast decisions are not always wise. Requiring a majority or supermajority ensures careful deliberation and protects against impulsive decisions.

When Governance Changes Cause Conflict

I’ve observed a rise in litigation tied to governance changes, especially when:

  • Membership definitions are altered
  • Bylaws are revised without transparency

Courts are increasingly weighing inโ€”especially when the dispute involves corporate governance rather than doctrine.

Key Legal Insight

Judges often side with long-term attendees and donors who are excluded from decision-making, especially if they were not informed of bylaw changes. Courts can rule on corporate matters that don’t require interpreting religious doctrine.

A Notable Cautionary Tale: Mars Hill Church

Mars Hill never used a congregation-led model, but its downfall underscores the risks of governance consolidation.

Founded in 1996, Mars Hill grew to 12,000 weekly attendees across 15 campuses. In 2014, internal conflicts and leadership issues led to its collapse.

One key decision: Founder Mark Driscoll revised the bylaws to concentrate power among a small group of eldersโ€”including himself. This governance shift limited accountability and fueled the church’s downfall. (See The Rise and Fall of Mars Hill, Episode 7.)

Six Key Considerations Before Changing Governance

Churches considering a move from congregation-led to board-led structures should address these:

  1. Assess current governance: Review bylaws, incorporation documents, and denominational rules.
  2. Check state laws: Some states require congregational votes regardless of internal governance.
  3. Evaluate current model: Consider the reasons your church chose a congregation-led model.
  4. Explore alternatives: Could your goals be met within the existing model?
  5. Plan the process: How will you involve the congregation, communicate changes, and handle dissent?
  6. Handle legal updates: Revise incorporation documents and bylaws to align with new governance.

Proceed with Transparency and Caution

A governance change made in secrecy can devastate a church. The Mars Hill story offers a strong caution: concentrated power with no accountability can create lasting damage.

Additional Resources

  • Podcast: Erika Cole interviews Rise and Fall of Mars Hill creator Mike Cosper on church governance
  • Bottom line: Donโ€™t shrink decision-making to a few voices without careful review and counsel. Always consult experienced legal advisors before making major governance changes.
Erika E. Cole, Esq., known as The Church Attorneyยฎ, is one of only a handful of attorneys in the nation who practices exclusively in the area of church law. She currently serves as a senior editorial advisor for Christianity Todayโ€™s ChurchLawAndTax.com.

Church Formation Basics

Church formation basics gives leaders insights into how a church is formed, why it matters, and how it guides future decisions.

Last Reviewed: October 23, 2023

Loading the player...

Church formation basics is important because how a church is legally formed directly affects how it operates.

From articles of incorporation to bylaws to tax status, church leaders must understand how their church is formed and how that formation shapes the decisions they make, and the ways they make those decisions.

In this helpful, hands-on video, attorney Lisa Runquist, a longtime advisor for Church Law & Tax, delves deeper into the formation processes for churches and explains how the pieces that are essential to formation become instrumental to how those churches function, both internally and externally for years to come.

Download the slids to follow along and take notes as you watch.

Editorโ€™s Note. This video is exclusive to Church Law & Tax members only. However, you can sign-up here to watch this video for free.

Lisa A. Runquist has more than 40 years of experience as a transactional lawyer, both with nonprofit organizations and business organizations.
Related Topics:

Ask Richie

๐Ÿ‘‹ Hello! I'm Richie, your AI assistant. How can I help you today?
ajax-loader-largecaret-downcloseHamburger Menuicon_amazonApple PodcastsBio Iconicon_cards_grid_caretChild Abuse Reporting Laws by State IconChurchSalary Iconicon_facebookGoogle Podcastsicon_instagramLegal Library IconLegal Library Iconicon_linkedinLock IconMegaphone IconOnline Learning IconPodcast IconRecent Legal Developments IconRecommended Reading IconRSS IconSubmiticon_select-arrowSpotify IconAlaska State MapAlabama State MapArkansas State MapArizona State MapCalifornia State MapColorado State MapConnecticut State MapWashington DC State MapDelaware State MapFederal MapFlorida State MapGeorgia State MapHawaii State MapIowa State MapIdaho State MapIllinois State MapIndiana State MapKansas State MapKentucky State MapLouisiana State MapMassachusetts State MapMaryland State MapMaine State MapMichigan State MapMinnesota State MapMissouri State MapMississippi State MapMontana State MapMulti State MapNorth Carolina State MapNorth Dakota State MapNebraska State MapNew Hampshire State MapNew Jersey State MapNew Mexico IconNevada State MapNew York State MapOhio State MapOklahoma State MapOregon State MapPennsylvania State MapRhode Island State MapSouth Carolina State MapSouth Dakota State MapTennessee State MapTexas State MapUtah State MapVirginia State MapVermont State MapWashington State MapWisconsin State MapWest Virginia State MapWyoming State IconShopping Cart IconTax Calendar Iconicon_twitteryoutubepauseplay
caret-downclosefacebook-squarehamburgerinstagram-squarelinkedin-squarepauseplaytwitter-square